


Contractor For House Repair Letter Size Overview
Many people mistakenly assume that all wood types provide the same heat output, but this is far from the truth. The wood btu chart is a valuable tool that dispels this myth, offering a clear, data-driven way to compare wood types and their energy content. This chart is a straightforward reference, presenting the heat output, or BTU (British Thermal Unit), of various woods, which helps you make informed choices about firewood selection and usage. While the exact values may vary slightly depending on factors like moisture content, the wood btu chart provides a reliable guide to understanding wood fuel efficiency and heat output per cord.
A Practical Guide to the Wood BTU Chart
The wood BTU chart is a valuable tool for anyone using wood as a fuel source. It provides a clear and concise reference for understanding the heating potential of different wood types. This chart offers a quick and easy way to compare the energy content of various woods, helping you make informed decisions about fuel efficiency.
Comparing Wood Types and Their BTU Values
The wood BTU chart typically presents a range of common wood species, each with its own heating value, measured in BTUs (British Thermal Units). You'll find familiar woods like oak, maple, and pine, each with its unique energy content. The chart may also include less common varieties, offering a comprehensive overview. These values represent the heat output per unit of wood, allowing you to compare the efficiency of different woods.
Step-by-Step Guide to Using the Wood BTU Chart
Using the wood BTU chart is straightforward. First, identify the wood type you are interested in. Then, locate it on the chart and note the BTU value. This value represents the heat energy released when burning a specific amount of that wood. For instance, if you're using oak, you might find it has a higher BTU value than softer woods like pine, indicating its superior heating potential. This simple process allows you to choose the most suitable wood for your needs.
Avoiding Common Misreadings and Pitfalls
It's essential to understand that the values on the wood BTU chart are approximate and can vary. Factors like moisture content and wood density can significantly impact the actual heating value. Wet wood, for example, will have a lower BTU output than dry wood of the same type. Always ensure the wood you're using is well-seasoned and has the standard firewood moisture content of around 20% for accurate results.
Key Factors Affecting Accuracy and Real-World Use
- Moisture Content: The moisture level in wood is a critical factor. Wet wood burns inefficiently and produces less heat.
- Wood Species: Different woods have varying natural densities and energy contents.
- Seasoning Time: Properly seasoned wood is essential for accurate BTU calculations.
- Cord Measurements: Ensure you understand the standard heat output per cord to make accurate comparisons.
- Regional Variations: Some charts may have regional differences, so check the applicable standards.
Remember, while the wood BTU chart is a valuable tool, it's just a guide. Always consider the specific conditions and requirements of your situation for the most accurate and efficient wood fuel use.
Your wood BTU chart is a handy tool, a quick reference guide to keep close by. It offers a simple yet effective way to compare and understand the energy content of different wood types, an essential step when planning your fuel sources.
Remember, while this chart provides a great starting point, it's always wise to double-check the specific requirements for your project or situation. Exact values can vary, so ensure you have the right data for your needs. Bookmark this page for future reference; it might just save you some time and effort down the line!
Related: RSMeans Estimating Essential Guide For Builders
RSMeans estimating... it's a term I've come across recently, and I was curious to know more. As someone who's dabbled in home renovations and heard about construction projects, I wanted to understand what this phrase means and how it relates to the world of building and remodeling. So, let's dive in and uncover the secrets behind RSMeans estimating!
Unraveling the Mystery: What is RSMeans Estimating?
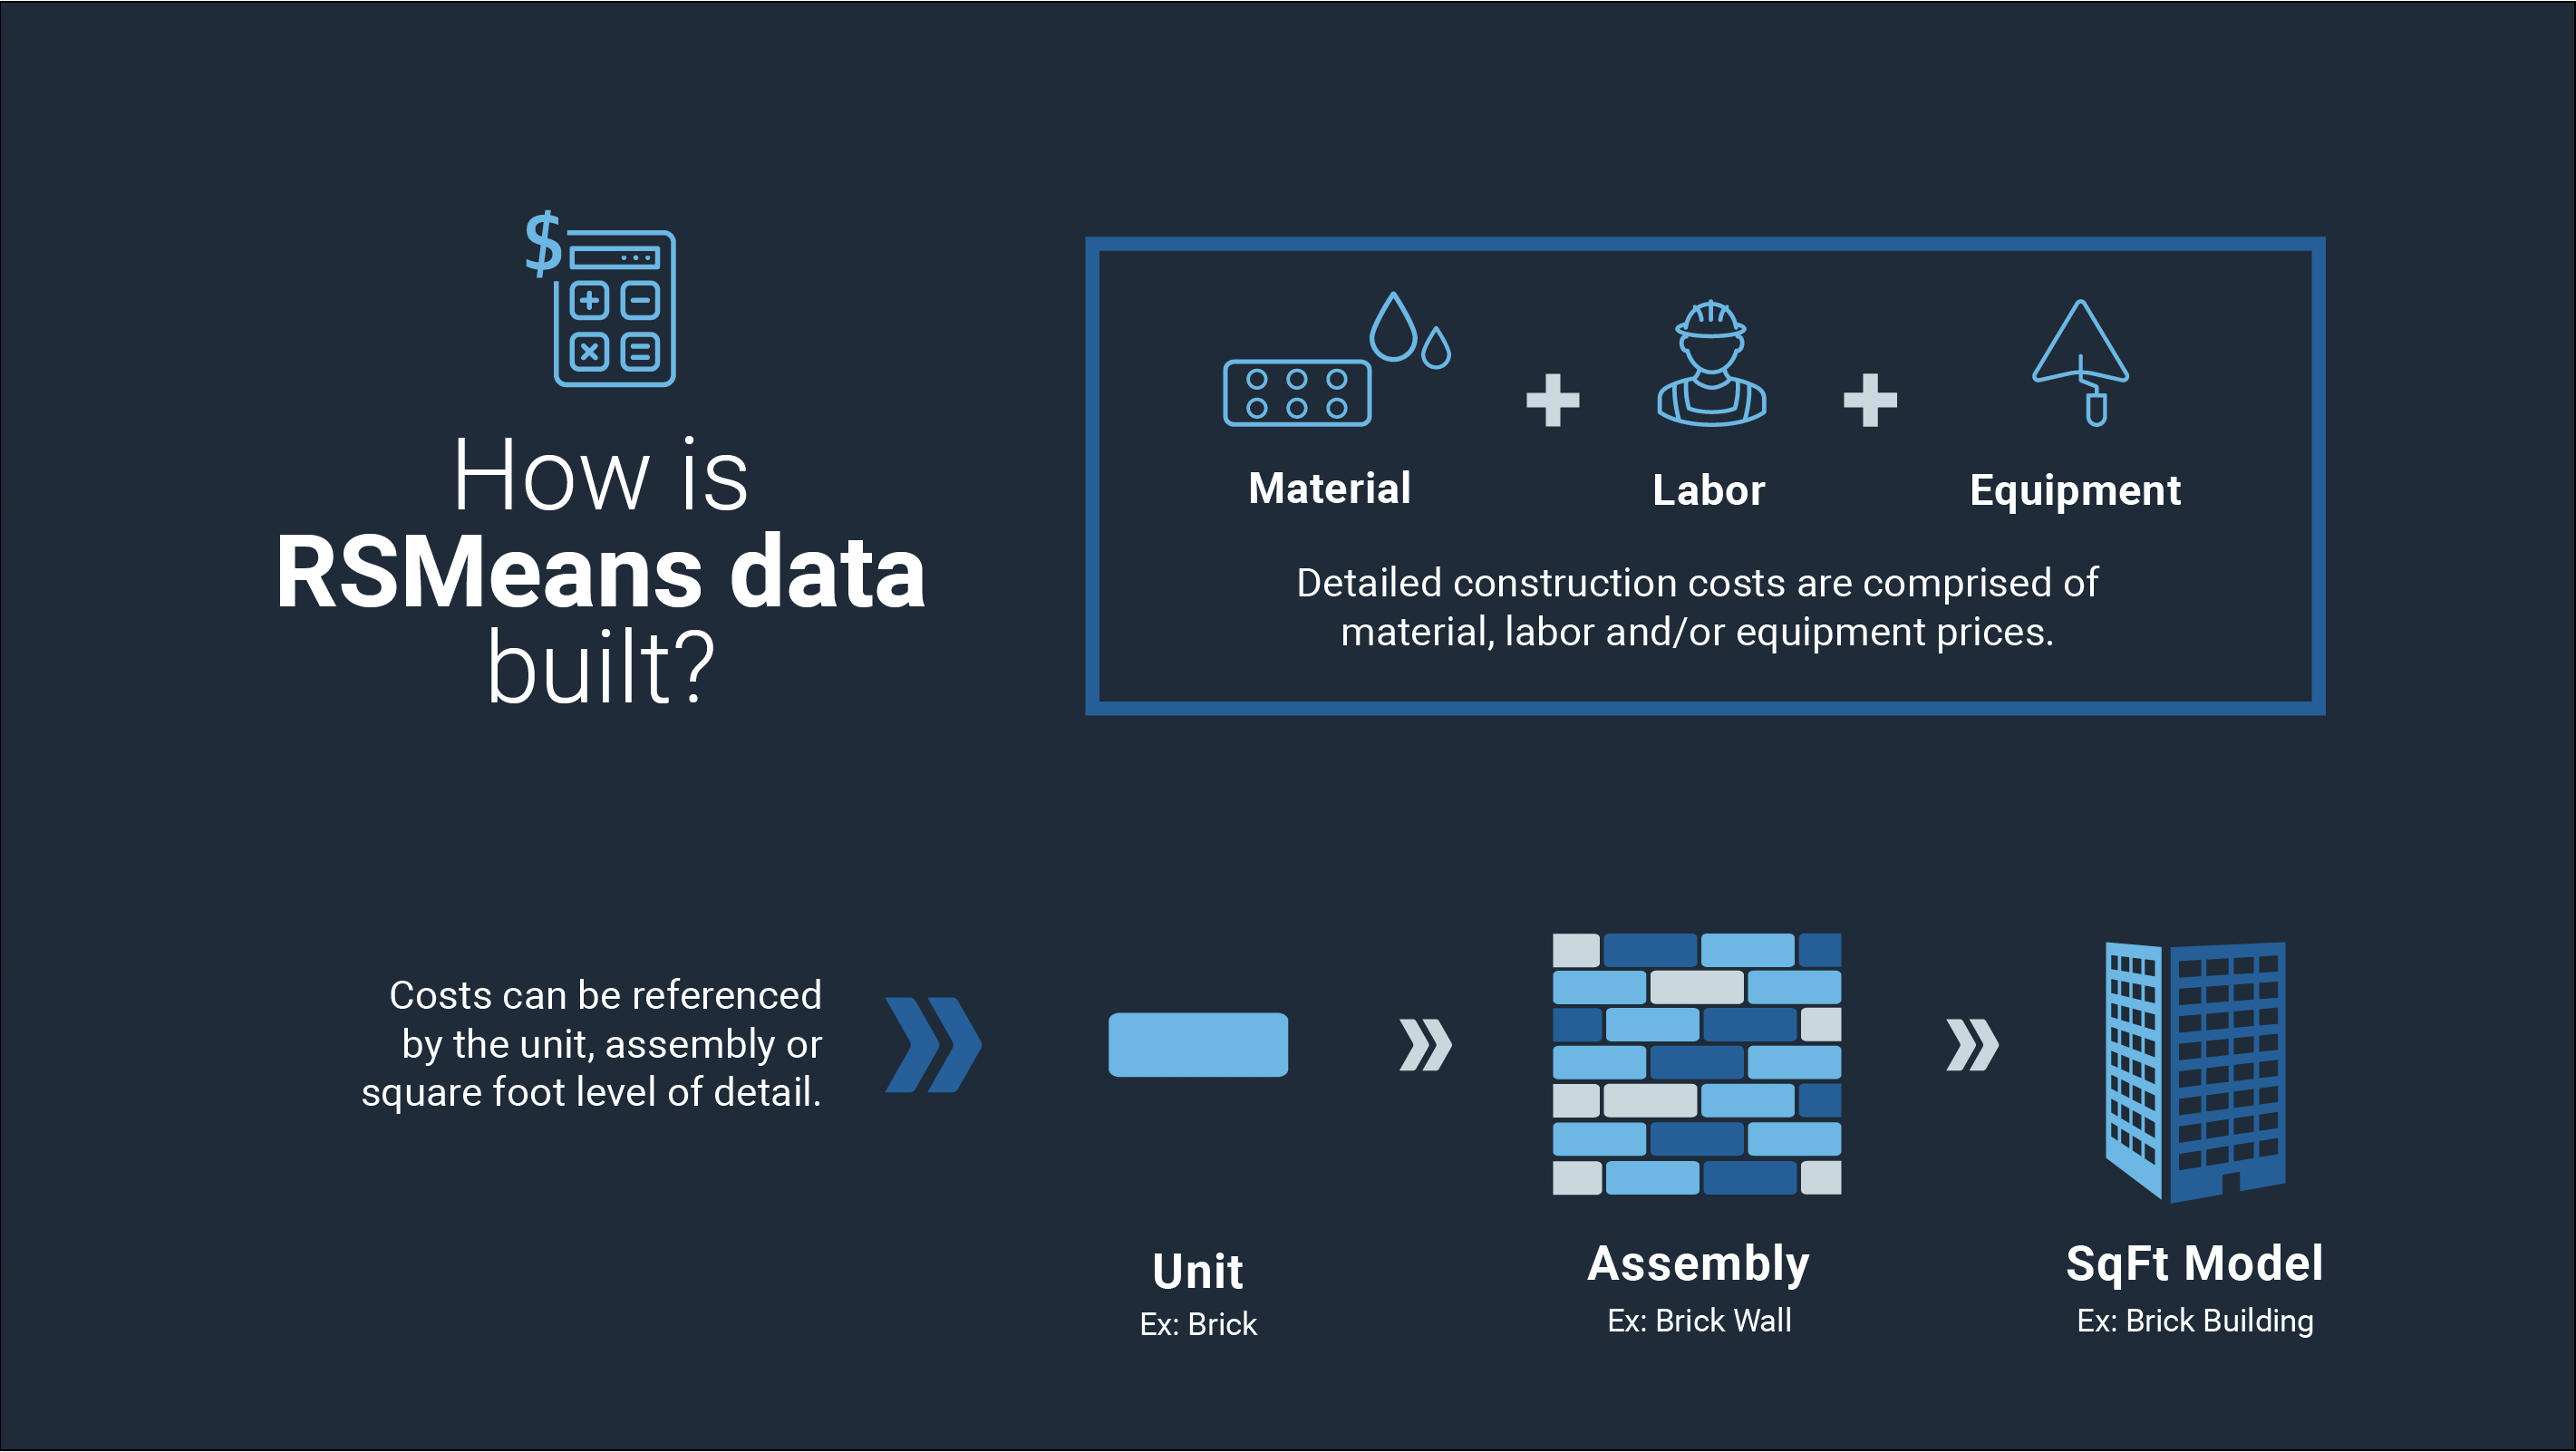
RSMeans estimating is a tool, a resource, and a method used by construction professionals to estimate the costs and pricing of various projects. It's like a handy guide that helps builders, contractors, and even homeowners like me make informed decisions. This estimating process considers factors like labor, materials, and the overall scope of the work to provide an accurate cost estimate.
For those of us considering a home renovation, understanding RSMeans estimating can be a game-changer. It empowers us to compare quotes, ensure we're getting a fair deal, and make smart choices about our projects. Whether it's a bathroom renovation or a full-scale house addition, having a reliable estimate is crucial.
Hiring the Right Contractor: A Guide
When it comes to hiring a contractor for your project, RSMeans estimating can be a valuable tool. It helps you evaluate quotes and understand the breakdown of costs. Here's a simple guide:
- Check the contractor's experience and reputation.
- Ask for references and read reviews.
- Get multiple quotes and compare them.
- Ensure the quote covers all aspects of the job.
- Look for transparency and clear communication.
A good quote should detail the work, materials, and labor costs. It should also include any potential additional expenses, like permits or unexpected issues. Remember, it's not just about the lowest price; it's about finding a reliable and skilled contractor who understands your vision.
Construction Business Names: A Creative Challenge
Naming a construction business is an art! It's a chance to be creative and leave a lasting impression. A great name should be memorable, reflect your company's values, and stand out in a competitive market. Here are a few ideas:
- BuildCraft
- HomeWorkz
- SkyRise Solutions
- EarthMovers
- Brick & Mortar Pros
- BuildTech Innovations
Before settling on a name, check its availability for domains and local registration. You want to ensure your business name is unique and can be easily found online.
The World of Construction Jobs
The construction industry offers a wide range of roles, from estimators to project managers and skilled laborers. Estimator jobs, for instance, involve using tools like RSMeans to calculate costs accurately. These professionals are in demand and play a crucial role in the success of projects.
If you're interested in construction jobs, explore online job boards, local newspapers, and industry-specific websites. Many construction companies also advertise directly on their websites, so it's worth keeping an eye out for openings.
RSMeans: A Powerful Tool for Professionals
RSMeans is a trusted resource in the construction industry. It provides cost databases, escalation data, and cost indexes, helping professionals make informed decisions. Whether you're a general contractor or a remodeling company, RSMeans estimating offers valuable insights.
This tool is especially useful when planning projects, as it helps anticipate costs and stay within budget. It's a go-to resource for many in the industry, providing accurate and up-to-date information.
Big vs. Small: The Construction Industry Landscape
The construction industry is diverse, with both large corporations and small, local businesses. Large firms often have the resources to take on major projects and offer a wide range of services. They may have a broader reach and access to more specialized skills.
Small businesses, on the other hand, can provide a more personalized experience. They often have a strong local presence and can offer competitive pricing. When choosing a company, consider your project's scope and your preferences for size and expertise.
In conclusion, RSMeans estimating is a valuable tool for anyone involved in construction, remodeling, or building projects. It empowers us to make informed decisions, compare costs, and ensure a successful outcome. So, whether you're in Atlanta, Baltimore, or San Francisco, RSMeans estimating is a resource worth exploring!
Related: outlook unsend email Simple Excel tracker for recall
The Art of Budgeting: Mastering Your Finances
Understanding the Basics of Budgeting
Budgeting is the foundation of financial health. It involves tracking income, categorizing expenses, and allocating funds to meet both short-term needs and long-term goals. A well-structured budget ensures you live within your means, save consistently, and avoid debt. The core principle is simple: spend less than you earn. However, the execution requires discipline and a clear plan.
Start by listing all sources of income, including salary, side gigs, or investments. Next, categorize expenses into fixed (rent, utilities) and variable (groceries, entertainment). Use tools like spreadsheets, apps, or notebooks to track spending. The 50/30/20 rule is a popular framework: 50% for needs, 30% for wants, and 20% for savings and debt repayment.
Creating a Realistic Budget Plan
A realistic budget aligns with your lifestyle and financial goals. Begin by analyzing past spending to identify patterns. For instance, if you spend $400 monthly on dining out, allocate that amount but consider reducing it gradually. Prioritize essentials like housing and food before discretionary spending.
Worked Example:
Imagine your monthly income is $4,000. Using the 50/30/20 rule:
- Needs (50%): $2,000 (e.g., $1,200 rent, $300 utilities, $500 groceries).
- Wants (30%): $1,200 (e.g., $400 dining, $300 entertainment, $500 shopping).
- Savings/Debt (20%): $800 (e.g., $500 emergency fund, $300 student loan).
Adjust categories based on your priorities. For example, if you’re saving for a house, reduce wants and increase savings.
Common Mistake: Overestimating Income or Underestimating Expenses
A frequent error is assuming consistent income or overlooking irregular expenses. For instance, freelancers might base their budget on a high-income month, only to struggle during slower periods. Similarly, forgetting annual expenses like insurance premiums can derail your plan.
Fix: Use your lowest consistent income as the baseline. For irregular expenses, divide the annual cost by 12 and set aside that amount monthly. Example: A $600 annual car insurance policy requires saving $50 monthly.
Tracking and Adjusting Your Budget
Budgeting isn’t a set-it-and-forget-it task. Regularly monitor your spending to ensure you stay on track. Weekly check-ins help catch overspending early. If you consistently exceed a category, reassess its allocation or cut back in another area.
Tools for Effective Budgeting
Leverage technology to simplify budgeting. Apps like Mint, YNAB, or Excel templates automate tracking and provide insights. For manual tracking, a notebook or bullet journal works well. The key is consistency—choose a method that fits your lifestyle.
Budgeting for Irregular Income
If your income varies, budgeting requires extra planning. Calculate your average monthly income over the past year and use that as your baseline. Allocate funds to a savings buffer during high-income months to cover lows.
Example:
If your monthly income ranges from $2,500 to $4,500, average it to $3,500. Save the surplus during high-income months in a separate account.
Common Mistake: Neglecting Emergency Funds
Many budgets focus on daily expenses but ignore emergencies. Without a safety net, unexpected costs like car repairs can lead to debt.
Fix: Prioritize building an emergency fund covering 3-6 months of living expenses. Start small—even $20 weekly adds up over time.
Budgeting for Long-Term Goals
Incorporate long-term goals like retirement, homeownership, or education into your budget. Use retirement accounts (e.g., 401(k), IRA) and high-yield savings for specific goals.
Example:
To save $20,000 for a down payment in 5 years, allocate $333 monthly. Adjust for interest or investment returns if applicable.
Dealing with Debt in Your Budget
Debt repayment should be a priority. Use the debt snowball (pay smallest debts first) or avalanche (pay highest-interest debts first) method. Allocate at least the minimum payments in your budget, with extra funds toward high-interest debt.
Common Mistake: Ignoring Small Expenses
Daily coffee or subscription services can add up quickly. These small expenses often go unnoticed but significantly impact your budget.
Fix: Track every expense, no matter how small. Cut non-essential subscriptions and limit impulse purchases.
Budgeting as a Family
Family budgeting requires collaboration. Hold regular financial meetings to discuss goals and progress. Teach children about money management by involving them in budgeting decisions.
Example:
Allocate $100 monthly for family outings and let kids decide how to spend it within that limit.
Adapting Your Budget Over Time
Life changes—new jobs, marriages, or children—require budget adjustments. Review your budget quarterly to reflect new circumstances.
Common Mistake: Being Too Rigid
A budget that’s too restrictive leads to frustration and abandonment. Allow flexibility for occasional treats or unexpected needs.
Fix: Include a "miscellaneous" category for unplanned expenses or occasional indulgences.
The Psychological Aspect of Budgeting
Budgeting isn’t just about numbers; it’s about mindset. Celebrate small wins, like paying off a credit card, to stay motivated. View budgeting as a tool for freedom, not restriction.
Example:
Reward yourself with a movie night after sticking to your budget for three months.
Budgeting for Special Occasions
Plan for holidays, birthdays, or vacations in advance. Set aside a small amount monthly to avoid financial stress during these events.
Example:
For a $1,000 holiday budget, save $83 monthly starting in January.
Common Mistake: Relying on Credit for Budget Shortfalls
Using credit cards to cover budget gaps leads to debt accumulation. Interest charges compound the problem, making repayment harder.
Fix: Reduce expenses or increase income to cover shortfalls. If necessary, use a 0% interest credit card temporarily but pay it off before the promotional period ends.
Budgeting for Retirement
Start early to maximize retirement savings. Contribute to employer-matched plans and explore tax-advantaged accounts like Roth IRAs.
Example:
If your employer matches 5% of your salary, contribute at least that amount to get the full benefit.
Final Thoughts on Budgeting
Budgeting is a dynamic process that evolves with your life. Stay committed, be flexible, and focus on progress, not perfection. With time, it becomes second nature, paving the way for financial security and peace of mind.