
Funny Forty Birthday Wishes Overview
You've landed on this page, so you're probably seeking a quick, reliable guide to skate steam charts. These charts are an essential tool for anyone working with steam systems, offering a clear and concise reference for steam pressure and its applications. It's a simple yet powerful resource, providing a snapshot of the key values and their uses. The beauty of skate steam charts is their versatility; they can vary depending on your specific needs and context, making them a handy, adaptable reference.
Understanding the Skate Steam Chart: A Quick Overview
The skate steam chart is a valuable tool for anyone working with steam-powered equipment, especially in the world of skating. It provides a visual representation of the relationship between steam pressure and the corresponding skate performance or behavior. This chart is your guide to understanding how steam pressure impacts your skating experience.
Comparing Steam Pressure Standards and Categories
When it comes to steam pressure, there are different units and standards to consider. The most common skate steam charts use pounds per square inch (psi) or bars as the pressure unit. These charts often cover a range of pressures, typically from 0 to 100 psi or 0 to 7 bars, which are the standard operating pressures for most skate steam applications.
How to Use the Skate Steam Chart: A Step-by-Step Guide
Identify the steam pressure you're working with. This could be the pressure your steam generator is producing or the pressure your equipment is designed to handle.
Locate the pressure value on the chart's horizontal axis. This axis typically represents steam pressure and is labeled with the unit of measurement (psi or bars).
Follow the vertical line corresponding to your identified pressure until it intersects with the chart's curve or line graph.
Read the value on the vertical axis, which represents the resulting skate performance or behavior. This could be skate speed, maneuverability, or any other relevant parameter.
Use this information to make informed decisions about your skate setup, maintenance, or adjustments.
Common Misreadings and How to Avoid Them
It's important to remember that skate steam charts are general guides and may not account for every unique skate or application. Here are some common misreadings and how to avoid them:
Overlooking Unit Conversion: Always ensure you're using the correct unit of measurement. If your equipment uses a different unit than the chart, convert the pressure value accordingly.
Assuming Universal Applicability: Skate steam charts provide general guidelines. Always refer to your skate's manual or manufacturer's specifications for exact pressure tolerances and performance characteristics.
Neglecting Environmental Factors: Steam pressure behavior can be influenced by temperature, altitude, and other environmental conditions. Consider these factors when interpreting the chart's data.
Factors Affecting Accuracy and Real-World Use
Several key factors can influence the accuracy of a skate steam chart and its real-world application:
Skate Type and Design: Different skate types and designs may respond uniquely to steam pressure. High-performance skates, for example, might have different pressure-performance curves than recreational models.
Steam Quality and Consistency: The quality and consistency of the steam your equipment produces can impact its performance. Ensure your steam generator is well-maintained and operating optimally.
Environmental Conditions: As mentioned, temperature, humidity, and altitude can affect steam behavior and, consequently, skate performance. Consider these factors when interpreting the chart.
Maintenance and Wear: Regular maintenance and timely replacement of worn-out parts can ensure your skate responds accurately to steam pressure as indicated by the chart.
By understanding these factors and using the skate steam chart as a practical guide, you can make informed decisions about your skate's performance and ensure a safe and enjoyable skating experience.
Well, there you have it! We've covered a lot of ground and hopefully, you now feel equipped to navigate the world of skate steam charts with ease. Remember, these charts are a fantastic tool, but it's always wise to double-check the specifics for your unique situation.
Don't forget to explore our other guides; we have a range of resources to help you master various topics. Happy reading, and keep rolling with those charts!
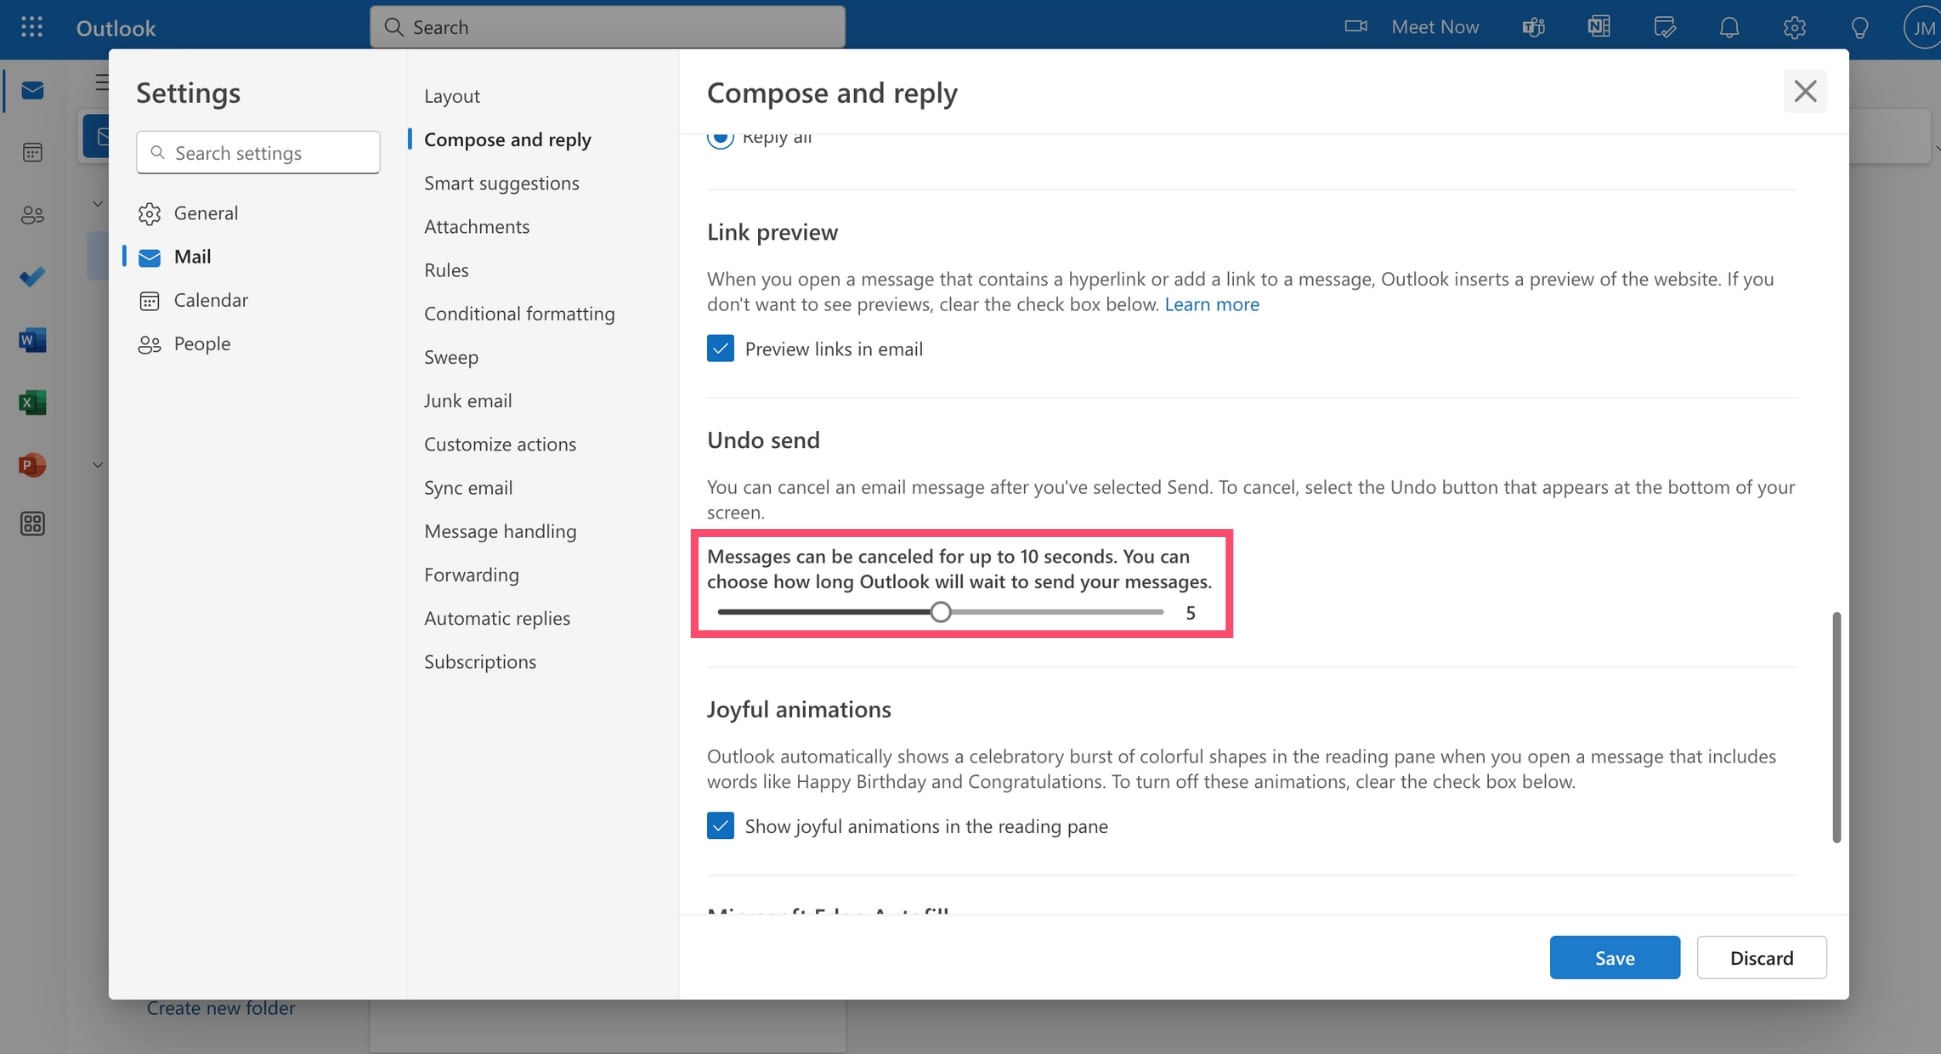
Related: outlook unsend email Simple Excel tracker for recall
The Art of Budgeting: Mastering Your Finances
Understanding the Basics of Budgeting
Budgeting is the foundation of financial health. It involves tracking income, categorizing expenses, and allocating funds to meet both short-term needs and long-term goals. A well-structured budget ensures you live within your means, save consistently, and avoid debt. The core principle is simple: spend less than you earn. However, the execution requires discipline and a clear plan.
Start by listing all sources of income, including salary, side gigs, or investments. Next, categorize expenses into fixed (rent, utilities) and variable (groceries, entertainment). Use tools like spreadsheets, apps, or notebooks to track spending. The 50/30/20 rule is a popular framework: 50% for needs, 30% for wants, and 20% for savings and debt repayment.
Creating a Realistic Budget Plan
A realistic budget aligns with your lifestyle and financial goals. Begin by analyzing past spending to identify patterns. For instance, if you spend $400 monthly on dining out, allocate that amount but consider reducing it gradually. Prioritize essentials like housing and food before discretionary spending.
Worked Example:
Imagine your monthly income is $4,000. Using the 50/30/20 rule:
- Needs (50%): $2,000 (e.g., $1,200 rent, $300 utilities, $500 groceries).
- Wants (30%): $1,200 (e.g., $400 dining, $300 entertainment, $500 shopping).
- Savings/Debt (20%): $800 (e.g., $500 emergency fund, $300 student loan).
Adjust categories based on your priorities. For example, if you’re saving for a house, reduce wants and increase savings.
Common Mistake: Overestimating Income or Underestimating Expenses
A frequent error is assuming consistent income or overlooking irregular expenses. For instance, freelancers might base their budget on a high-income month, only to struggle during slower periods. Similarly, forgetting annual expenses like insurance premiums can derail your plan.
Fix: Use your lowest consistent income as the baseline. For irregular expenses, divide the annual cost by 12 and set aside that amount monthly. Example: A $600 annual car insurance policy requires saving $50 monthly.
Tracking and Adjusting Your Budget
Budgeting isn’t a set-it-and-forget-it task. Regularly monitor your spending to ensure you stay on track. Weekly check-ins help catch overspending early. If you consistently exceed a category, reassess its allocation or cut back in another area.
Tools for Effective Budgeting
Leverage technology to simplify budgeting. Apps like Mint, YNAB, or Excel templates automate tracking and provide insights. For manual tracking, a notebook or bullet journal works well. The key is consistency—choose a method that fits your lifestyle.
Budgeting for Irregular Income
If your income varies, budgeting requires extra planning. Calculate your average monthly income over the past year and use that as your baseline. Allocate funds to a savings buffer during high-income months to cover lows.
Example:
If your monthly income ranges from $2,500 to $4,500, average it to $3,500. Save the surplus during high-income months in a separate account.
Common Mistake: Neglecting Emergency Funds
Many budgets focus on daily expenses but ignore emergencies. Without a safety net, unexpected costs like car repairs can lead to debt.
Fix: Prioritize building an emergency fund covering 3-6 months of living expenses. Start small—even $20 weekly adds up over time.
Budgeting for Long-Term Goals
Incorporate long-term goals like retirement, homeownership, or education into your budget. Use retirement accounts (e.g., 401(k), IRA) and high-yield savings for specific goals.
Example:
To save $20,000 for a down payment in 5 years, allocate $333 monthly. Adjust for interest or investment returns if applicable.
Dealing with Debt in Your Budget
Debt repayment should be a priority. Use the debt snowball (pay smallest debts first) or avalanche (pay highest-interest debts first) method. Allocate at least the minimum payments in your budget, with extra funds toward high-interest debt.
Common Mistake: Ignoring Small Expenses
Daily coffee or subscription services can add up quickly. These small expenses often go unnoticed but significantly impact your budget.
Fix: Track every expense, no matter how small. Cut non-essential subscriptions and limit impulse purchases.
Budgeting as a Family
Family budgeting requires collaboration. Hold regular financial meetings to discuss goals and progress. Teach children about money management by involving them in budgeting decisions.
Example:
Allocate $100 monthly for family outings and let kids decide how to spend it within that limit.
Adapting Your Budget Over Time
Life changes—new jobs, marriages, or children—require budget adjustments. Review your budget quarterly to reflect new circumstances.
Common Mistake: Being Too Rigid
A budget that’s too restrictive leads to frustration and abandonment. Allow flexibility for occasional treats or unexpected needs.
Fix: Include a "miscellaneous" category for unplanned expenses or occasional indulgences.
The Psychological Aspect of Budgeting
Budgeting isn’t just about numbers; it’s about mindset. Celebrate small wins, like paying off a credit card, to stay motivated. View budgeting as a tool for freedom, not restriction.
Example:
Reward yourself with a movie night after sticking to your budget for three months.
Budgeting for Special Occasions
Plan for holidays, birthdays, or vacations in advance. Set aside a small amount monthly to avoid financial stress during these events.
Example:
For a $1,000 holiday budget, save $83 monthly starting in January.
Common Mistake: Relying on Credit for Budget Shortfalls
Using credit cards to cover budget gaps leads to debt accumulation. Interest charges compound the problem, making repayment harder.
Fix: Reduce expenses or increase income to cover shortfalls. If necessary, use a 0% interest credit card temporarily but pay it off before the promotional period ends.
Budgeting for Retirement
Start early to maximize retirement savings. Contribute to employer-matched plans and explore tax-advantaged accounts like Roth IRAs.
Example:
If your employer matches 5% of your salary, contribute at least that amount to get the full benefit.
Final Thoughts on Budgeting
Budgeting is a dynamic process that evolves with your life. Stay committed, be flexible, and focus on progress, not perfection. With time, it becomes second nature, paving the way for financial security and peace of mind.
Related: What Does "Off the Charts" Really Mean?
You're here because you need a quick answer, a reliable reference for a chart that's got you stumped. Maybe it's a body mass index (BMI) chart, or a weight-height ratio guide - these can be off the charts confusing! It's easy to feel lost when you're trying to understand the categories and ranges, especially as they can vary depending on where you are and who you ask. But don't worry, we'll get you on track with a simple breakdown. These charts are designed to give you a snapshot of your health, and with a few key insights, you'll be reading them like a pro.
Understanding Body Mass Index (BMI): What It Means to Be "Off the Charts"
Body Mass Index, or BMI, is a simple calculation that helps give an indication of whether your weight is in a healthy range for your height. It's a useful tool to get an overview of your health, but it's not the only measure of health or fitness. So, what does it mean when someone is "off the charts" with their BMI? Let's find out!
Key Details and Categories to Know
The BMI chart is a visual representation of the BMI calculation, which is your weight (in kilograms) divided by the square of your height (in meters). The result is then compared to a standard range to determine your BMI category. These categories are: underweight (below 18.5), healthy weight (18.5 to 24.9), overweight (25 to 29.9), and obese (30 or above). The chart often uses colors or shading to represent these categories, making it easy to see where you fall.
Step-by-Step Guide: Reading and Interpreting Your BMI
To use the BMI chart accurately, follow these steps:
- Weigh yourself and note your weight in kilograms.
- Measure your height accurately and convert it to meters (if needed).
- Square your height (multiply it by itself).
- Divide your weight by the squared height.
- Locate your BMI on the chart.
- Identify the color or category it falls into.
For example, if your BMI is 28, you would be in the overweight category. It's a simple process, but remember, it's just one tool to assess your health.
Variations and Differences: Why BMI Can Vary
It's important to understand that BMI can vary due to several factors. Age, muscle mass, and bone density can all affect your BMI. For instance, highly muscular individuals might have a higher BMI but not be overweight or obese. Additionally, BMI charts and categories can differ slightly depending on the standard used. Some charts might have slightly different ranges or categories, so always check which standard is being used.
- Key factors that can cause BMI variations:
- Muscle mass
- Bone density
- Age
- Body composition
Common Mistakes and How to Avoid Them
When using the BMI chart, be aware of these potential mistakes:
- Assuming BMI is the only health indicator: It's just one tool, so consider other factors like diet, exercise, and overall well-being.
- Forgetting to convert units: Always ensure your height is in meters and weight in kilograms for an accurate calculation.
- Not considering individual differences: BMI is a general guide; it might not apply accurately to everyone.
- Relying solely on the chart: It's a visual aid, but the calculation is more precise.
Remember, being "off the charts" with BMI doesn't always mean there's a health issue. It's a guide, and understanding your individual circumstances is key.
Well, that's a wrap on our exploration of this handy reference tool! We've covered the basics, from understanding the key elements to navigating any variations you might encounter. Remember, while the fundamentals remain consistent, exact details can shift based on your specific context or the source you're referencing.
Feel free to dive into our other guides for more practical tips and tricks. We've got a whole library of resources to help you master various topics, so take a browse and find something that piques your interest!