Schedule Email Outlook Sheet Overview
I've just been thinking about all the construction going on around me lately, and it got me curious about construction outlook. You know, all those new builds and renovations, it's like a whole new world springing up. So, I decided to dig a bit deeper and see what's up with the construction game these days.
Understanding Construction Outlook
Construction outlook is basically a big-picture view of the construction industry. It's about understanding the trends, the costs, and the opportunities in the world of building and renovating. For anyone planning a project, whether it's a new home, an addition, or a renovation, having a handle on the construction outlook is super important. It can help you make informed decisions and avoid any nasty surprises.
So, what does it entail? Well, it's about keeping an eye on things like material costs, labor rates, and the general demand for construction services. These factors can vary wildly depending on your location and the specific project you have in mind. For example, in a place like San Francisco, you might expect higher costs due to the high demand for construction and the limited space, whereas a city like Helena might have a different set of challenges and opportunities.
Hiring and Costs
When it comes to hiring contractors or companies, the construction outlook can give you a good idea of what to expect. It's all about comparing quotes and understanding what you're paying for. You want to check out the scope of the work, the materials being used, and the timeline. A good quote will cover all these bases and more. It's also worth remembering that the cheapest quote might not always be the best. Sometimes, you get what you pay for, and construction is no exception.
Company Names and the Industry
For those in the industry, or thinking of starting a construction business, choosing a name is a big deal. It needs to be memorable, reflect your services, and be unique. Some construction companies go for a more traditional, descriptive name, like 'Atlanta Building Solutions', while others opt for something more creative, like 'Build-It-Right'. Either way, it's important to check the name's availability and register it locally and online to avoid any legal headaches down the line.
Jobs and Opportunities
The construction industry offers a whole range of jobs, from general contractors to estimators and project managers. These roles can vary in terms of salary and responsibilities, but they all play a crucial part in bringing projects to life. If you're looking for construction jobs, you'll probably find opportunities listed on job boards and company websites. It's a good idea to check out the larger construction firms, as they often have more diverse roles to offer.
Tools and Resources
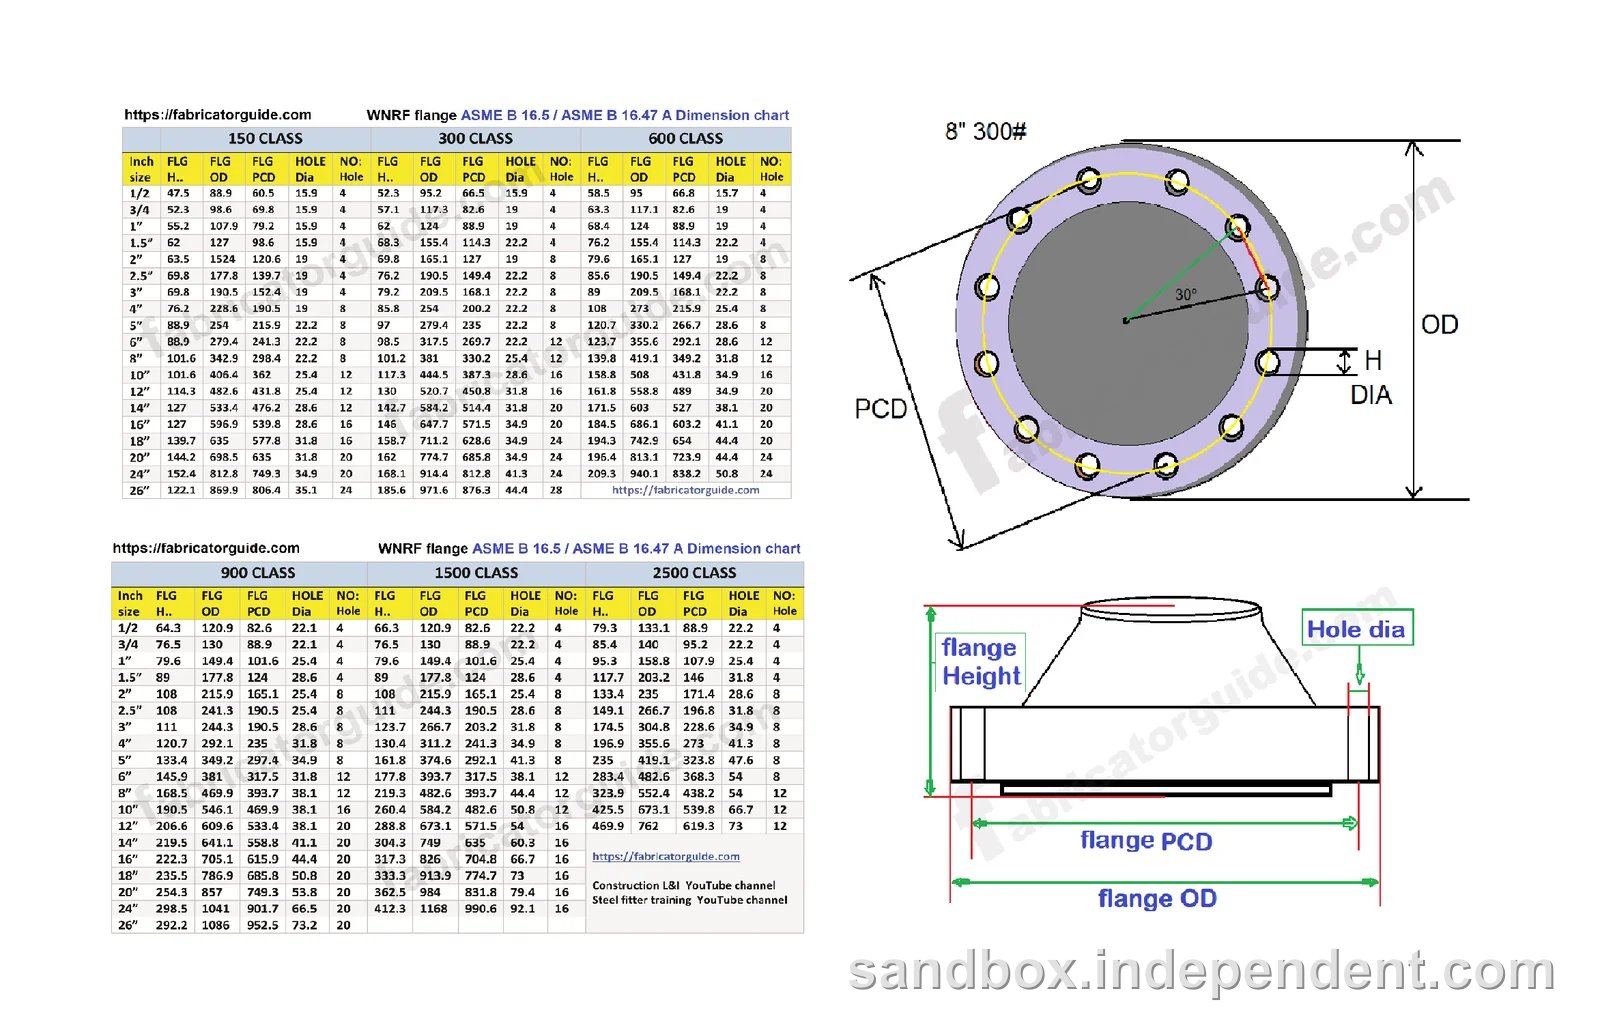
There are also some great tools and resources out there to help with construction outlook. For example, RSMeans is a popular cost database that provides estimates for a range of construction projects. It's a handy resource for anyone wanting to get a handle on costs and stay informed about industry trends. There are also plenty of other cost indexes and databases out there, each with their own strengths and weaknesses.
The Big Picture
When it comes to the bigger construction companies, they often have the resources to take on larger, more complex projects. These firms might have a wider reach and the ability to offer a broader range of services. However, smaller companies can often provide a more personalized service and might be a better fit for certain projects. It all depends on your specific needs and the nature of your project.
So, there you have it. A little insight into construction outlook and what it means for those in the industry and those planning projects. It's a fascinating world, and one that's constantly evolving.
I hope this has given you some food for thought and a better understanding of the construction game. It's always good to be informed!
Related: outlook unsend email Simple Excel tracker for recall
The Art of Budgeting: Mastering Your Finances
Understanding the Basics of Budgeting
Budgeting is the foundation of financial health. It involves tracking income, categorizing expenses, and allocating funds to meet both short-term needs and long-term goals. A well-structured budget ensures you live within your means, save consistently, and avoid debt. The core principle is simple: spend less than you earn. However, the execution requires discipline and a clear plan.
Start by listing all sources of income, including salary, side gigs, or investments. Next, categorize expenses into fixed (rent, utilities) and variable (groceries, entertainment). Use tools like spreadsheets, apps, or notebooks to track spending. The 50/30/20 rule is a popular framework: 50% for needs, 30% for wants, and 20% for savings and debt repayment.
Creating a Realistic Budget Plan
A realistic budget aligns with your lifestyle and financial goals. Begin by analyzing past spending to identify patterns. For instance, if you spend $400 monthly on dining out, allocate that amount but consider reducing it gradually. Prioritize essentials like housing and food before discretionary spending.
Worked Example:
Imagine your monthly income is $4,000. Using the 50/30/20 rule:
- Needs (50%): $2,000 (e.g., $1,200 rent, $300 utilities, $500 groceries).
- Wants (30%): $1,200 (e.g., $400 dining, $300 entertainment, $500 shopping).
- Savings/Debt (20%): $800 (e.g., $500 emergency fund, $300 student loan).
Adjust categories based on your priorities. For example, if you’re saving for a house, reduce wants and increase savings.
Common Mistake: Overestimating Income or Underestimating Expenses
A frequent error is assuming consistent income or overlooking irregular expenses. For instance, freelancers might base their budget on a high-income month, only to struggle during slower periods. Similarly, forgetting annual expenses like insurance premiums can derail your plan.
Fix: Use your lowest consistent income as the baseline. For irregular expenses, divide the annual cost by 12 and set aside that amount monthly. Example: A $600 annual car insurance policy requires saving $50 monthly.
Tracking and Adjusting Your Budget
Budgeting isn’t a set-it-and-forget-it task. Regularly monitor your spending to ensure you stay on track. Weekly check-ins help catch overspending early. If you consistently exceed a category, reassess its allocation or cut back in another area.
Tools for Effective Budgeting
Leverage technology to simplify budgeting. Apps like Mint, YNAB, or Excel templates automate tracking and provide insights. For manual tracking, a notebook or bullet journal works well. The key is consistency—choose a method that fits your lifestyle.
Budgeting for Irregular Income
If your income varies, budgeting requires extra planning. Calculate your average monthly income over the past year and use that as your baseline. Allocate funds to a savings buffer during high-income months to cover lows.
Example:
If your monthly income ranges from $2,500 to $4,500, average it to $3,500. Save the surplus during high-income months in a separate account.
Common Mistake: Neglecting Emergency Funds
Many budgets focus on daily expenses but ignore emergencies. Without a safety net, unexpected costs like car repairs can lead to debt.
Fix: Prioritize building an emergency fund covering 3-6 months of living expenses. Start small—even $20 weekly adds up over time.
Budgeting for Long-Term Goals
Incorporate long-term goals like retirement, homeownership, or education into your budget. Use retirement accounts (e.g., 401(k), IRA) and high-yield savings for specific goals.
Example:
To save $20,000 for a down payment in 5 years, allocate $333 monthly. Adjust for interest or investment returns if applicable.
Dealing with Debt in Your Budget
Debt repayment should be a priority. Use the debt snowball (pay smallest debts first) or avalanche (pay highest-interest debts first) method. Allocate at least the minimum payments in your budget, with extra funds toward high-interest debt.
Common Mistake: Ignoring Small Expenses
Daily coffee or subscription services can add up quickly. These small expenses often go unnoticed but significantly impact your budget.
Fix: Track every expense, no matter how small. Cut non-essential subscriptions and limit impulse purchases.
Budgeting as a Family
Family budgeting requires collaboration. Hold regular financial meetings to discuss goals and progress. Teach children about money management by involving them in budgeting decisions.
Example:
Allocate $100 monthly for family outings and let kids decide how to spend it within that limit.
Adapting Your Budget Over Time
Life changes—new jobs, marriages, or children—require budget adjustments. Review your budget quarterly to reflect new circumstances.
Common Mistake: Being Too Rigid
A budget that’s too restrictive leads to frustration and abandonment. Allow flexibility for occasional treats or unexpected needs.
Fix: Include a "miscellaneous" category for unplanned expenses or occasional indulgences.
The Psychological Aspect of Budgeting
Budgeting isn’t just about numbers; it’s about mindset. Celebrate small wins, like paying off a credit card, to stay motivated. View budgeting as a tool for freedom, not restriction.
Example:
Reward yourself with a movie night after sticking to your budget for three months.
Budgeting for Special Occasions
Plan for holidays, birthdays, or vacations in advance. Set aside a small amount monthly to avoid financial stress during these events.
Example:
For a $1,000 holiday budget, save $83 monthly starting in January.
Common Mistake: Relying on Credit for Budget Shortfalls
Using credit cards to cover budget gaps leads to debt accumulation. Interest charges compound the problem, making repayment harder.
Fix: Reduce expenses or increase income to cover shortfalls. If necessary, use a 0% interest credit card temporarily but pay it off before the promotional period ends.
Budgeting for Retirement
Start early to maximize retirement savings. Contribute to employer-matched plans and explore tax-advantaged accounts like Roth IRAs.
Example:
If your employer matches 5% of your salary, contribute at least that amount to get the full benefit.
Final Thoughts on Budgeting
Budgeting is a dynamic process that evolves with your life. Stay committed, be flexible, and focus on progress, not perfection. With time, it becomes second nature, paving the way for financial security and peace of mind.
Related: how to change outlook signature quick steps to update
Need to know how to change outlook signature? This post walks you through the basics in a few easy steps.
You’ll learn where to find the signature settings, how to edit Outlook signature, and how to set an Outlook default signature for new messages. The steps are similar across recent versions, though some menu labels may vary slightly.
Quick answer: how to change outlook signature and add new signature
You can quickly add a new signature in Outlook with just a few clicks. how to change outlook signature works whether you use the desktop app or Outlook on the web.
The feature is limited to Microsoft 365 or Exchange accounts; POP/IMAP setups do not support signatures at all. If you see a warning that your account cannot use signatures, you need to switch to a supported account type.
In Outlook desktop, open File > Options > Mail and click Signatures…; in Outlook on the web, go to Settings > View all Outlook settings > Mail > Compose and reply. Outlook default signature is stored in that location and can be edited anytime.
Compare methods by version: edit existing signature for Outlook on the web and Outlook desktop app
The desktop Outlook for Windows has a dedicated Signatures dialog where you can edit existing signature with rich formatting, images, and hyperlinks. You can also set a default signature for new messages, replies, or forwards from the same pane.
Outlook on the web places the signature in a plain‑text box under Mail settings, and changes sync automatically to all signed‑in devices. The web version renders HTML, so spacing may look slightly different from the desktop client.
Outlook for Mac uses a similar Signatures pane in Preferences > Mail, letting you create and edit signatures with the same options as Windows. Export the signature as an .htm file to move it between platforms without losing formatting.
Step-by-step guide: edit existing signature in Outlook on the web compose window
This guide applies to Outlook for Windows and Outlook for Microsoft 365; the steps are identical. You need an Exchange or Microsoft 365 account, otherwise the Signatures button is hidden.
- Open Outlook and click File > Options > Mail.
- Click the Signatures… button to open the Signatures dialog.
- Select an existing signature to edit, or click New to create one.
- Edit the text, insert images, add hyperlinks, and format as desired.
- Under Choose default signature, set it for New messages and/or Replies/Forwards.
- Click OK to save your changes and close the dialog.
After saving, compose a new email to confirm the signature appears at the bottom; test a reply to see the reply‑signature behavior. If it doesn’t show, revisit the steps and verify the correct account is selected in the Signatures dialog.
Common mistakes and fixes: signature not appearing
A common slip is assigning a signature only for replies and forgetting to set it as the default for new messages; always verify both options in the Signatures dialog. The Outlook default signature setting is where you confirm the choice.
If the signature does not appear in Outlook on the web, open Settings > View all Outlook settings > Mail > Compose and reply and make sure the signature box is filled. It sometimes hides behind the More actions menu, so expand that section before saving.
Signatures are unavailable on POP/IMAP accounts, so switch to an Exchange or Microsoft 365 account if you see a notice. Images may be blocked for security; re‑insert them and allow inline attachments, or use plain text if the recipient’s client does not support HTML.
Prevent future issues: Outlook desktop app signature management
Keep your signature in one .htm file and import it on each PC to maintain consistent formatting. Copying the Outlook web app signature from the web version into the desktop compose window also works.
After a Windows or Office update, open the Signatures dialog and verify that your default signature is still selected; a new install can clear the selection. A quick monthly check prevents unexpected missing signatures in important messages.
For teams, ask IT to deploy a standard signature via Group Policy or the Microsoft 365 admin center; this ensures everyone uses the approved branding and legal text. Admins can also lock the signature settings so users cannot modify them.
When moving to Outlook on the web, export the desktop signature as an .htm file and paste it into the web compose box; this preserves tables, images, and hyperlinks. Preview the signature to confirm formatting before sending.
Finally, test your signature on several devices and email clients to ensure it appears as intended; adjust the content or switch to plain text if needed. how to change outlook signature becomes routine once you have a reliable workflow in place.
Menus can look a bit different depending on which version of Outlook you’re using, so don’t be surprised if things shift around a little.
If you liked this tip, take a look at the other Microsoft Office guides on the site for more quick fixes and how‑tos.